Most small business owners I’ve met didn’t study accounting, and honestly, they don’t need a full degree in it. But understanding a handful of basic accounting principles genuinely changes how confidently you run your business.
I’ve watched a shop owner in Jaipur go from constantly guessing his monthly profit to knowing it down to the rupee within three months, just by applying a few of these basics consistently.
The Accrual vs Cash Basis Distinction
In brief: Cash basis accounting records transactions only when money actually changes hands, while accrual basis records income and expenses when they’re earned or incurred, regardless of when payment happens.
Most small businesses start with cash basis because it’s simpler. But as you grow, especially with credit sales or delayed vendor payments, accrual accounting gives a far more accurate picture of actual financial health.
Understanding the Balance Sheet
A balance sheet shows what your business owns (assets), owes (liabilities), and what’s left over (equity) at a specific point in time. It’s basically a financial snapshot, not a story over time.
- Assets: cash, inventory, equipment, receivables
- Liabilities: loans, unpaid bills, credit card dues
- Equity: what’s genuinely yours after subtracting liabilities from assets
[link to related guide on business registration process here]
Reading a Profit and Loss Statement
In brief: A profit and loss statement (P&L) shows revenue, expenses, and resulting profit or loss over a specific period, helping business owners understand whether operations are genuinely profitable, not just busy.
I’ve seen business owners proudly point to strong revenue numbers while completely ignoring that expenses had grown just as fast. Revenue without profit context is a bit of a trap.
The Matching Principle
This principle states that expenses should be recorded in the same period as the revenue they helped generate. It sounds technical, but practically it means: don’t record a big marketing expense in January if the sales it generated actually land in March.
Understanding Cash Flow vs Profit
This trips up more business owners than almost anything else. A business can be profitable on paper and still run out of cash, especially if customers pay late or inventory ties up funds.
Has this happened to you — good sales numbers, but somehow still struggling to pay a supplier on time? That’s a cash flow problem, not a profit problem, and the fix is different.
Alt text suggestion: “Small business owner reviewing accounting principles and financial statements”
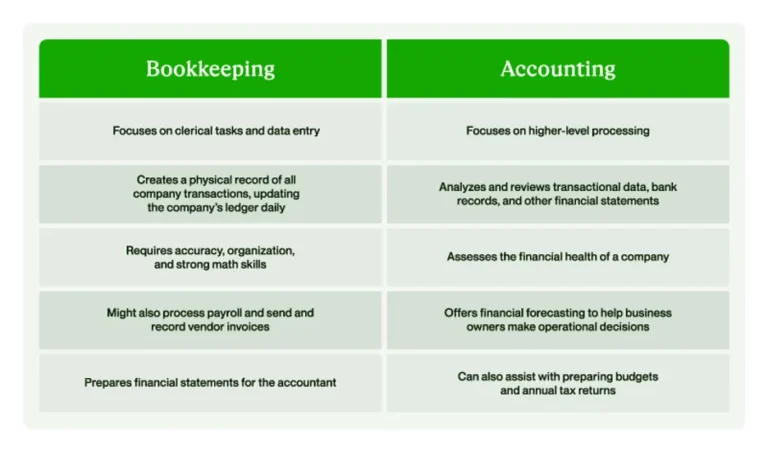
[link to related guide on bookkeeping vs accounting here]
The Conservatism Principle
This principle suggests recording expenses and liabilities as soon as they’re probable, but only recording revenue when it’s actually earned and reasonably certain. It keeps businesses from overstating how well things are going.
Consistency in Accounting Methods
Whatever method you choose — cash or accrual, straight-line or reducing balance depreciation — stick with it consistently across periods. Switching methods frequently makes it nearly impossible to compare performance year over year, and can raise red flags during audits.
FAQ
What are the most basic accounting principles a small business owner should know? Understanding the difference between cash and accrual accounting, reading a P&L statement, and separating cash flow from profit are the essential starting points.
Do I need an accountant if I understand these basics? Yes, ideally still. Basic accounting principles help you understand your numbers, but a professional ensures compliance with tax laws and proper filing.
What’s the difference between profit and cash flow? Profit is revenue minus expenses on paper; cash flow is the actual money moving in and out of your bank account, which can differ significantly due to timing.
Why does the matching principle matter for small businesses? It prevents misleading profit figures by ensuring expenses are recorded alongside the revenue they actually helped generate, giving an accurate period-by-period view.
Can I switch between cash and accrual accounting anytime? Technically possible but not recommended frequently — consistency helps with accurate year-over-year comparisons and simplifies tax compliance.
Conclusion
You don’t need to become an accountant to run a financially healthy business — you just need a working grasp of these basic accounting principles. Understanding your balance sheet, P&L, and the real difference between cash and profit puts you back in control of decisions that used to feel like guesswork.
Start by reviewing last month’s P&L statement properly, line by line. You’ll likely spot something you didn’t expect.